What to Do When a Parent Isn’t Paying for the Wedding They Promised
Get the new number in writing, close the gap in the right order and keep the relationship. Below: scripts for the talk, what $292 a guest means for your list, what a card costs at 19.63%, whether the promise is binding and a 60-day plan.
Numbers checked 30 September 2026, with a source on every one.
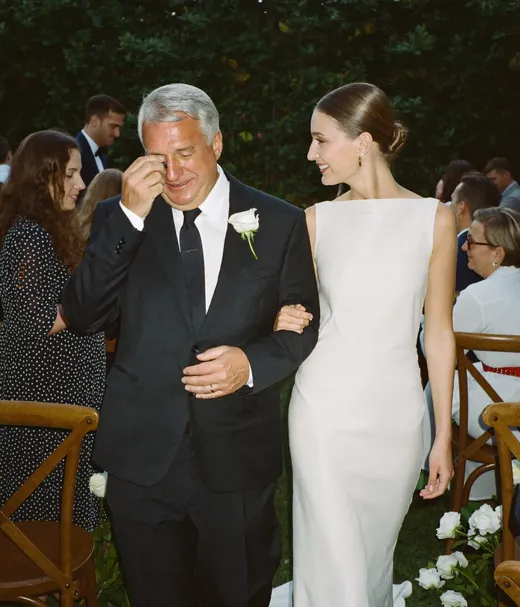 He still walks you down the aisle
- 20 fewer guests · at $292 a guest$5,840
- Second photographer dropped · vendor scope$1,200
- Saved from pay over 60 days · own money$1,960
What do you do when a parent stops paying for the wedding?
Pause new vendor payments, have one calm talk to learn the real amount and timing, and confirm it in a text. Then close the gap in this order: cut guests (about $292 each on average), trim vendor scope, move your own savings, ask other family, and borrow last. A promise to pay for a wedding is usually a gift, not a contract, so treat it as a family conversation, not a debt to collect.
71%
of 2026 weddings get some money from family, per Zola’s survey of 11,500+ couples
88%
of couples pay part or all of it themselves: 29% fully, 59% partly, per Zola
$292
a guest is what the average wedding costs, per The Knot 2026 Real Weddings Study
19.63%
is the average credit card APR on 30 September 2026, per Bankrate
Sources: Zola First Look Report 2026, The Knot 2026 Real Weddings Study ($34,200 for 117 guests) and Bankrate. The budget in the hero is illustrative: $15,000 promised, $6,000 given, a $9,000 gap. Checked 30 September 2026.
Why the money stopped changes what you say
Most pullbacks fall into one of four kinds. Name yours before the talk, because the right opening line is different for each one.
Money got tight
A job loss, a health bill, a market drop. The promise was real; the money is not there anymore.
What to doTake the new number with grace and ask what they can give: a smaller amount, a later date or one specific thing.
The numbers never matched
They pictured $5,000 and you heard $15,000, or they thought it covered the whole wedding.
What to doPut the real quotes on the table and agree on a fixed amount, not a share of an unknown total.
Something broke
A fight, a divorce, a new partner, a clash over the guest list or the venue.
What to doHave the relationship talk first. Money talks go nowhere while the hurt is still open.
Money with strings
The money comes back if you invite their friends, pick their venue or change the officiant.
What to doDecide what the money is worth to you. You can say no to the strings, and to the money.
You are not alone in needing help: LendingTree found 16% of newlyweds paid for the wedding mainly with help from parents or relatives, and Zola found 71% of 2026 weddings get some family money. When that money moves, the whole plan moves with it.
What to say to the parent who pulled the money
Go in for the number, not the reason. One calm talk, then one friendly text that puts the amount, what it covers and the date where nobody can forget it.
Before the talk
- 1Know your numbers: what is booked, what is paid, what is due and when.
- 2Agree with your partner on what you need and what you can let go of.
- 3Pick a calm time in person or on a call, never by text and never at a family event.
Lines that keep it calm
- “We’re not upset about the amount. We just need to know the real number so we can plan. What can you put in, and when?”
- “Is it the total or the timing? If spreading it over a few months helps, tell us.”
- “Would it help if your part went to one thing, like the venue deposit?”
- “If money isn’t possible right now, that’s okay. We’d still love your help with the rehearsal dinner.”
- “Can we put the new number in a text, so neither of us has to remember it?”
“But you promised.”
It starts a trial, not a plan.
“You paid for my sister’s wedding.”
It turns the talk into a fight about fairness.
Threats to cut the guest list or contact
They trade a budget problem for a family one.
A wedding planner on the money talk with your parents
Wedding planner Jamie Wolfer explains how to start the money conversation with your parents, the talk most couples dread, and how to make it less hard. Useful before a first talk and before a second one.
Watch on YouTube8 ways to cover the money, cheapest first
Ranked by what they cost you, not by how easy they feel. Rose chips mark the cell that most often rules an option out.
The guest list is the biggest lever and costs no money: at $292 a guest on average, 20 fewer guests is $5,840. Do it before invitations go out, then trim scope and move savings. Borrow last.
| Option | What it can close | What it costs you | How fast | The catch |
|---|---|---|---|---|
Cut the guest listStart here | About $292 a guest on average: 20 guests is $5,840 | Hard conversations, no money | Days, if invitations are not out | Much harder once invitations are out, so do it first |
| Trim vendor scope | A second photographer, late-night food, a bar upgrade, extra rentals | Extras you wanted | Days to a week | Check each contract for minimums and change fees |
| Change the date or day | Off-peak months and non-Saturday dates often price lower; ask each vendor | Vendors may be booked on the new date | 1 to 2 weeks | Deposits do not always move with you; read the contract first |
| Your own savings or income | Whatever you can set aside before the final payments | Slower progress on other goals | Weeks to months | Leaves a thinner cushion after the wedding |
| Ask other family | It varies; 69% of couples with family help get it from both sides, per Zola | An awkward ask | Weeks | New money can bring new opinions |
| Personal loan | The amount you qualify for | Interest and a monthly payment long after the day | Days | Only 4% of 2026 couples took out a loan, per Zola |
| Credit card | Up to your limit | 19.63% average APR: $10,000 at $300 a month costs $4,571 in interest | Same day | The most expensive way to close a gap |
| Postpone | Time to save the whole gap | Deposits and dates you may lose | Months | Deposits are often nonrefundable; price the move before you decide |
Swipe to compare all 8
Per-guest cost from The Knot 2026 Real Weddings Study, family help and loans from Zola’s First Look Report, card APR from Bankrate. Interest computed at 19.63% with monthly compounding. Checked 30 September 2026.
How many guests close the gap
The Knot puts the average wedding at $34,200 for 117 guests, $292 a guest. Your own number is your catering, bar and rentals per head, so check your quotes, but the average is a fast first read.
20 fewer guests is $5,840
$292 a guest from The Knot 2026 Real Weddings Study. Fixed costs like the dress or the photographer do not shrink with the list. Checked 30 September 2026.
One rule for both families
- 01Plus-ones for guests not in a relationshipThe cleanest rule, and easy to explain.
- 02Coworkers and work friendsUnless they are close friends outside work too.
- 03Guests you have not seen in 3 yearsOne rule for both families keeps it fair.
- 04Kids, other than familyAn adults-only reception trims the count fast.
Not sure who will come? Start with how to estimate the final guest count.
Scan. Upload.
Every guest’s view.
Watch a guest scan the QR code and add photos from the phone browser in seconds, with no app and no account. A smaller guest list still fills one album from every angle of the day.
WEDDING ALBUM
Lena & Marcus
Example album
Lena & Marcus
Added by Aunt June
A smaller wedding, every guest photo
Fewer guests often means closer photos. Share one link or a QR code and guests add photos and videos from the phone browser, with no app and no account. The first 20 uploads are free, so it costs nothing to try.
The grandmas, still dancing
Scan to join the album
No app, no account
UPLOADING
Saving your moment
THE ALBUM
Lena & Marcus
Example album
164 photos · 19 guests
SCAN TO TRY
pix.wedding/
your-wedding
What borrowing the gap really costs
A card closes the gap today and bills you for years. At the average APR of 19.63%, the interest on a wedding balance can pay for a honeymoon.
$10,000 at $300 a month: 49 months, $4,571 extra
APR from Bankrate. Months and interest computed with monthly compounding and no new charges. Your card’s rate may differ.
67%
of newlyweds took on debt for the wedding, per LendingTree’s survey.
4%
of 2026 couples took out a loan for the wedding, per Zola. Most close the gap other ways.
If you borrow, borrow the smallest amount for the shortest time, and set the payoff date before you sign.
Survey figures from LendingTree and Zola’s First Look Report 2026. Checked 30 September 2026.
Can you hold a parent to the money?
Almost never, and almost never worth trying. A promise to pay for a wedding is usually a promise of a gift. Here is how the law looks at it, in plain words. General information, not legal advice; rules differ by state.
A gift promise is usually not a contract
A contract needs something given on both sides. A parent’s offer to pay for the wedding usually asks nothing back, so it is a gift promise, and those generally cannot be enforced.
The narrow exception
Promissory estoppel lets a court enforce a promise when the person should have expected you to rely on it, you did rely on it to your detriment, and only enforcing it avoids injustice, per Cornell’s Legal Information Institute. Think: you signed a venue contract because of the promise.
Why court is still the wrong tool
It is slow, it costs money, and it puts your parent on the other side of a lawsuit before your wedding. If a large sum and signed contracts are at stake, ask a local lawyer first.
Money with strings, or money to pay back
If the money comes with conditions, ask what they are before you say yes, from any family member. If it has to be paid back, it is a loan: agree the amount and the schedule on paper, the same as you would with a bank. Clear terms now save a fight after the wedding.
When the wedding money turns into a debt
The Ramsey Show hosts take a call from a couple whose in-laws now want to be paid back for the wedding. Worth five minutes before you accept wedding money with conditions from anyone.
Watch on YouTubeDefinition from Cornell Law School’s Legal Information Institute. Checked 30 September 2026.
From the bad news to a new budget
Eight steps over about two months. Two weeks to talk and re-price, six weeks to rebuild. The dates move with your wedding date; the order does not.
- 01Days 1 to 3
Pause new payments
Hold off on signing or paying any new vendor until you know the real number. Payments already due still go out on time.
- 02Days 3 to 7
Have the talk
One calm conversation, in person or on a call. Ask what they can give and when, not why they changed their mind.
- 03Day 7
Get the number in writing
A short text or email with the amount, what it covers and the date. Friendly, not formal, and nobody has to remember it later.
- 04Days 7 to 14
Re-price the wedding
List every vendor: what is paid, what is due, when, and what the contract lets you change. That list is your real budget.
- 05Days 14 to 21
Cut the guest list first
At about $292 a guest, the list is the biggest lever you have. Cut before invitations go out, with one rule for both families.
- 06Days 21 to 30
Call the vendors
Ask about a smaller package, a lower minimum, another date and a later payment schedule. Get every change in writing.
- 07Days 30 to 45
Fund what is left
Set a weekly savings amount, ask other family if it fits, and borrow only for a small, short gap with a payoff date.
- 08Days 45 to 60
Lock the new budget
Write down the new total, share it with your partner and stop comparing it with the old plan.
Swipe for all 8 steps
The example on this page: $9,000 to close. Twenty fewer guests at $292 is $5,840, dropping the second photographer saves $1,200, and $245 a week for 8 weeks is $1,960. Total: $9,000, with no new debt. Illustrative numbers; use your own quotes. Put the new total into the wedding budget allocator to split it again.
8 questions that can lower a signed quote
Vendors field budget changes often. Call before a payment is due, lead with the number you can pay, and get every change in writing.
Ask every vendor
- 1Can we lower the guest count, and by what date?
- 2Is there a food and drink minimum, and is it lower on a Friday or Sunday?
- 3Can we move the date and keep the deposit?
- 4Can the payment schedule move later or split into more payments?
- 5Which items can we remove without a fee?
- 6Is there a smaller package with the same core service?
- 7What does the contract say about downsizing or cancelling?
- 8When is the final guest count due?
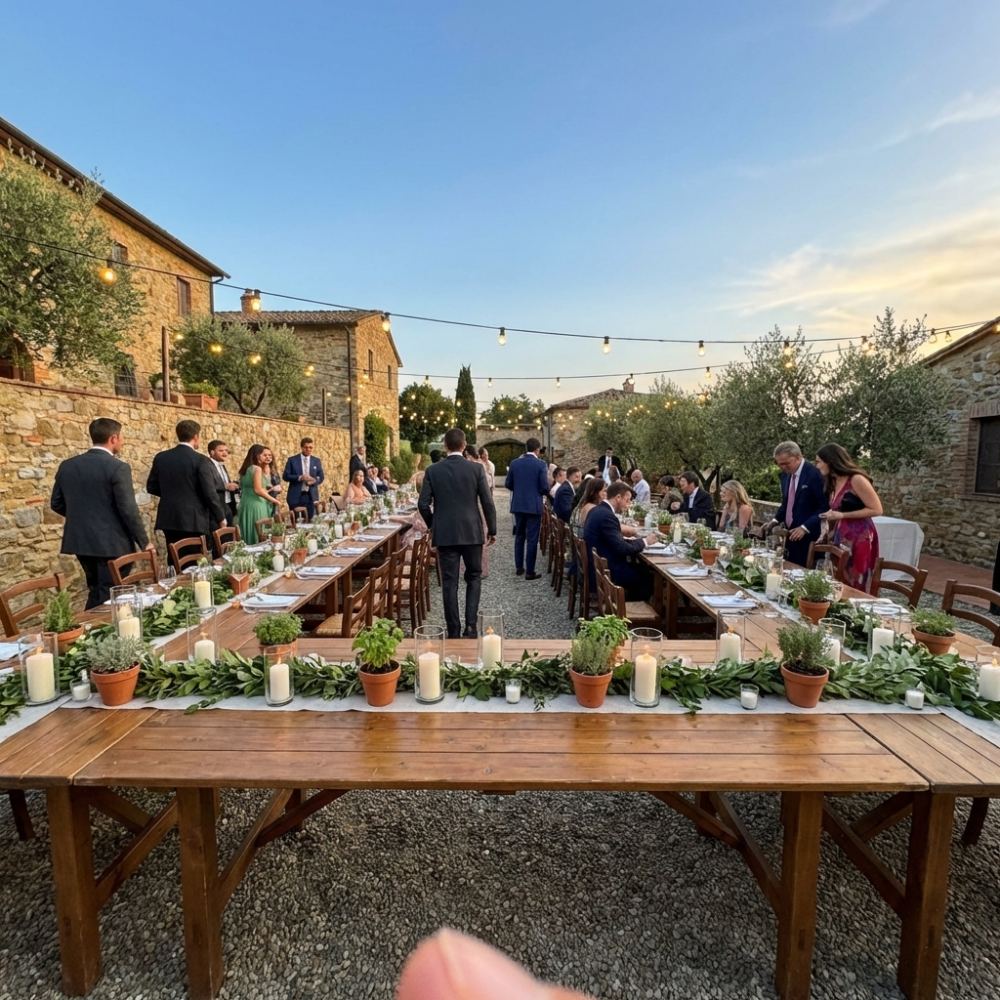
The same table, fewer chairs: catering, bar and rentals shrink with every seat.
Deposit
Refundable or not, and whether it moves to a new date.
Minimum
The minimum guest count or spend you owe even after cuts.
Cancellation
What you owe if you cancel or postpone, and by when.
Changes
Fees for changing the date, the package or the count.
A smaller budget is not a smaller marriage
A study of more than 3,000 married people in the US found that higher wedding spending was linked with shorter marriages, while more guests and a honeymoon were linked with longer ones. It shows a correlation, not a cause, but it is a useful check on the fear that less money means less wedding.
The types of weddings associated with lower likelihood of divorce are those that are relatively inexpensive but are high in attendance.
1.6x
the divorce hazard for women who spent $20,000 or more on the wedding, compared with $5,000 to $10,000.
Half
the divorce hazard for men who spent under $1,000 on the wedding, on the same comparison.
23% less
is what couples who pay 70% or more themselves spend on the wedding, per Zola.
The same study linked high attendance with longer marriages, so cut the guest list for the budget, not because smaller is better. Keep the people who matter; cut the plus-ones and the obligation invites. Study figures from Francis-Tan and Mialon, spending figure from Zola. Checked 30 September 2026.
Mistakes that make the gap bigger
Seven ways couples turn a money problem into a bigger money problem, or a family one, and the fix for each.
- 01
Paying vendors on the old budget
Every new deposit locks in a number you may not have anymore. Pause new spending for a few days.
- 02
Arguing about the promise, not the plan
Being right about what was said will not pay the caterer. Ask for the number and move on.
- 03
Leaving the new number verbal
Memories change under stress. A friendly text with the amount and the date saves a second fight.
- 04
Putting the whole gap on a card
At 19.63%, $10,000 paid at $300 a month takes 49 months and $4,571 in interest.
- 05
Taking new money without reading the strings
Ask what the money comes with before you say yes, from any family member.
- 06
Postponing before you price it
Lost deposits and a later date can cost more than a smaller wedding on the same day.
- 07
Telling every guest why
Guests need the new plan, not the family story. Keep the reason between you and your parent.
The quick check
Before any money decision this month, ask: is it in writing, is it the cheapest option left, and can we still talk to each other after it?
Do
- Ask for a fixed number and a date
- Confirm it in a friendly text
- Cut guests before invitations go out
- Call vendors before the next payment
- Keep your parent in the day
Don’t
- Argue about what was promised
- Sign new contracts on the old budget
- Put the whole gap on a card
- Take new money without asking the terms
- Share the family story with guests
Nobody on the dance floor knows what the budget was.
When a Parent Stops Paying: Common Questions
Quick answers on what to do first, whether the promise is binding, how to ask, borrowing, guest cuts, postponing, money with strings and who pays in 2026.
Pause any new vendor payments, then have one calm talk to learn the real amount and timing, and confirm it in a text. Re-price the wedding from your vendor contracts, cut the guest list first (about $292 a guest on average, per The Knot), trim vendor scope, and fund what is left from savings before you think about borrowing. Give the whole reset about 60 days.
Usually not. A promise to pay for a wedding is normally a promise of a gift, and a gift promise is generally not an enforceable contract. The narrow exception is promissory estoppel, which Cornell’s Legal Information Institute describes as enforcing a promise when you reasonably relied on it to your detriment. It is rare, slow and hard on the family. This is general information, not legal advice.
Ask early, in person, with your numbers ready, and ask for a fixed amount rather than a share of the total. Try: “We’re planning the budget and want to know what you’re comfortable with, and when.” Then confirm the amount, what it covers and the date in a short, friendly text.
Only for a small, short gap with a payoff date. The average credit card APR is 19.63% (Bankrate, 30 September 2026), so $10,000 paid at $300 a month takes 49 months and $4,571 in interest. LendingTree found 67% of newlyweds took on wedding debt, while only 4% of 2026 couples took out a loan, per Zola.
The Knot’s 2026 Real Weddings Study puts the average at $34,200 for 117 guests, or $292 a guest. At that rate, 10 fewer guests saves about $2,920, 20 saves $5,840 and 30 saves $8,760. Your per-guest cost is your catering, bar and rentals per head, so check your own quotes.
Price it first. Postponing gives you time to save, but deposits are often nonrefundable and vendors may not be free on a new date. Cutting guests and scope on the same date often costs less than moving. Postpone when the gap is bigger than what cuts and savings can close.
Treat conditions as part of the price. Ask exactly what the money comes with, decide together whether it is worth it, and get the terms in writing either way. If the money has to be paid back, it is a loan, so agree the amount and the schedule on paper.
Mostly the couple, with help. Zola’s 2026 First Look Report found 88% of couples pay part or all of it themselves (29% fully, 59% partly), and 71% of weddings get some family help. Among couples with family help, 69% get it from both families, so the old rule of the bride’s family paying for everything has faded.
Related guides
The budget, the guest list and the rest of the planning, plus the talks that come with it.
Sources, checked 30 September 2026
- The Knot 2026 Real Weddings Study
- Zola First Look Report 2026
- Zola: average cost of a wedding
- LendingTree: newlywed wedding debt survey
- Bankrate: current credit card interest rates
- Cornell LII: promissory estoppel
- Francis-Tan and Mialon, Economic Inquiry (2015)
Lena & Marcus, the budget, the text thread, the names, the times and the counts in the mockups on this page are illustrative. Photos are from our own library. Nothing here is legal or financial advice.
More free planning tools
Free tools for the budget, the guest list and the guest photos.
Cost Calculator
Compare wedding costs by city.
Budget Allocator
Turn your total into a category-by-category plan.
Courthouse Wedding Cost
Real fees by county and what to expect.
Photo Sharing QR
The best way to collect guest photos.
Wedding Checklist
Month-by-month planning checklist.
AI Vow Generator
Write "banger" vows in seconds.
AI Speech Pro
Banger toasts for Best Man & more.